Maximize Your 401(k) in 2026: The Ultimate Guide to Retirement Savings
Are you looking to secure your financial future and build a robust retirement nest egg? Understanding and effectively utilizing your 401(k) is paramount. As we look ahead to 2026, it’s crucial to stay informed about the latest contribution limits, strategies, and expert advice to ensure you’re making the most of this powerful retirement vehicle. This comprehensive guide will delve into everything you need to know to maximize 401(k) 2026 contributions and set yourself up for a comfortable retirement.
The 401(k) remains one of the most popular and effective ways for employees to save for retirement. Its tax advantages, coupled with potential employer matching contributions, make it an indispensable tool for long-term financial planning. However, many individuals don’t fully leverage its potential, leaving significant amounts of money on the table. By understanding the nuances of 401(k) plans and implementing smart strategies, you can significantly accelerate your path to financial independence.
Understanding the 401(k) Basics: Why It Matters to Maximize 401(k) 2026
Before diving into advanced strategies, let’s briefly review the fundamentals of a 401(k). A 401(k) is an employer-sponsored retirement savings plan that allows employees to invest a portion of their paycheck before taxes are withheld. This pre-tax contribution reduces your current taxable income, offering immediate tax savings. The money grows tax-deferred until retirement, when withdrawals are taxed as ordinary income. Some plans also offer a Roth 401(k) option, where contributions are made with after-tax dollars, but qualified withdrawals in retirement are tax-free.
Key Benefits of a 401(k):
- Tax Advantages: Pre-tax contributions lower your current taxable income. Earnings grow tax-deferred.
- Employer Match: Many employers offer to match a percentage of your contributions, essentially providing free money. This is often cited as one of the most compelling reasons to contribute, at least up to the match.
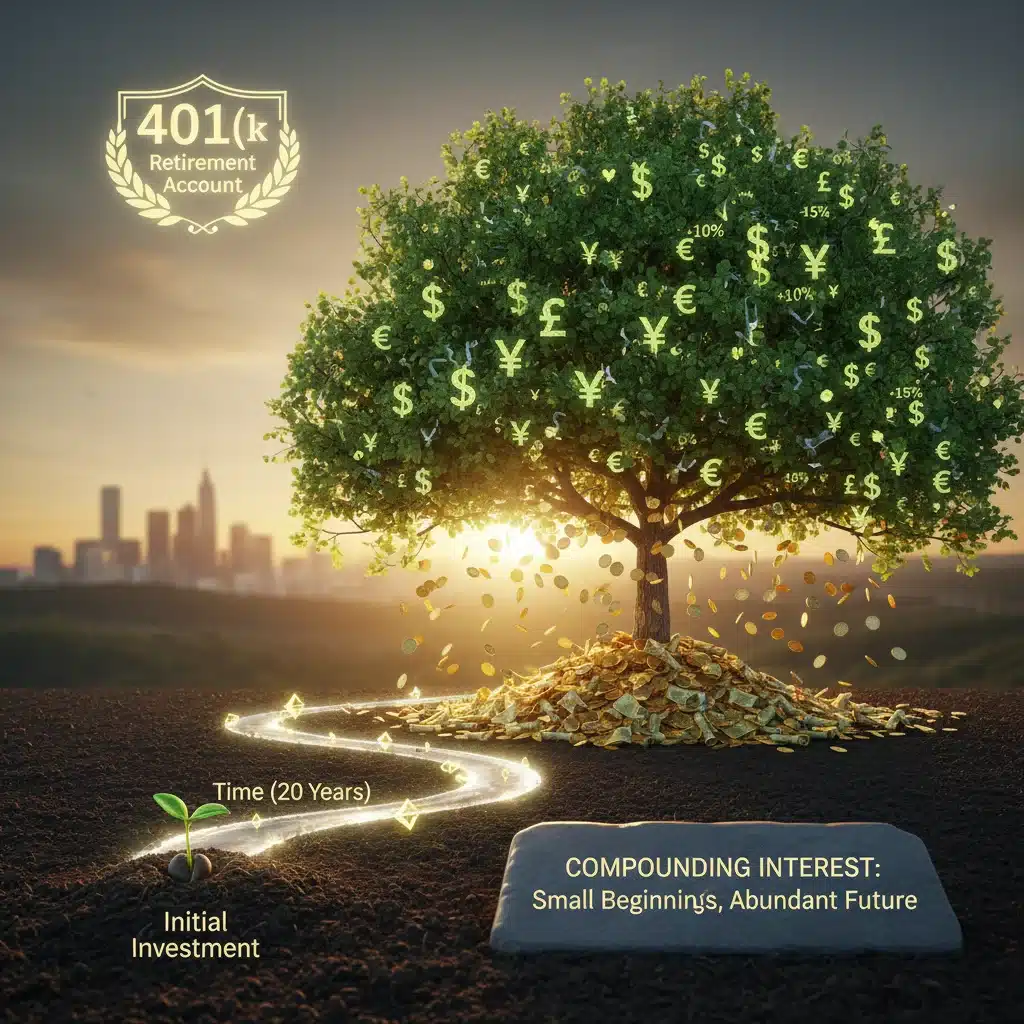
- Compounding Returns: The power of compounding allows your investments to grow exponentially over time, as earnings generate further earnings.
- Convenience: Contributions are typically automated through payroll deductions, making saving effortless.
- High Contribution Limits: 401(k) plans generally allow for higher contribution limits compared to other retirement accounts like IRAs.
To truly maximize 401(k) 2026, it’s essential to grasp these foundational benefits and how they contribute to your overall financial well-being.
Advertisements
Anticipated 401(k) Contribution Limits for 2026
While the official 401(k) contribution limits for 2026 are typically announced by the IRS in late 2025, we can make informed projections based on historical trends and inflation adjustments. The IRS generally adjusts these limits annually to account for inflation, using specific formulas. For 2025, the elective deferral limit for employees is expected to be around $23,500 to $24,000, with catch-up contributions for those aged 50 and over potentially reaching $7,500 to $8,000. For 2026, we can anticipate a slight increase from these figures.
Projected 2026 401(k) Contribution Limits:
- Employee Elective Deferral Limit: Expect this to be in the range of $24,000 – $25,500. This is the maximum amount you can contribute from your paycheck.
- Catch-Up Contribution Limit (Age 50+): For those aged 50 or older, an additional catch-up contribution is allowed. This is projected to be in the range of $7,500 – $8,500.
- Total 401(k) Contribution Limit (Employee + Employer): This limit encompasses contributions from both the employee and the employer (including matching and profit-sharing contributions). For 2026, this could be in the range of $69,000 – $72,000.
It’s vital to keep an eye on official IRS announcements towards the end of 2025 to confirm these figures. Once confirmed, adjust your contribution strategy accordingly to maximize 401(k) 2026 contributions right from the start of the new year.
Strategies to Maximize 401(k) 2026 Contributions
Simply knowing the limits isn’t enough; you need a strategic approach to hit those targets. Here are several effective strategies to help you maximize 401(k) 2026 contributions:
1. Contribute at Least Enough to Get the Full Employer Match
This is the golden rule of 401(k) saving. If your employer offers a match, contributing at least the minimum amount to receive the full match is essentially accepting free money. Failing to do so means leaving guaranteed returns on the table. For example, if your employer matches 50% of your contributions up to 6% of your salary, you should contribute at least 6% to get the full 3% match.
2. Front-Load Your Contributions (If Possible)
Some financial advisors suggest front-loading your 401(k) contributions at the beginning of the year. This means contributing a higher percentage of your salary early on to reach the annual limit sooner. The advantage is that your money has more time in the market to grow, potentially benefiting from an extra few months of compounding. However, be cautious if your employer’s matching contributions are based on per-paycheck contributions, as front-loading might cause you to miss out on some match if you hit the limit too early in the year. Check your plan’s specific rules regarding matching contributions.
3. Automate and Increase Contributions Annually
Set up automatic contributions directly from your paycheck. Then, make it a habit to increase your contribution percentage each year, especially when you receive a raise or bonus. Even a small increase, like 1% or 2% of your salary, can make a significant difference over decades due to the power of compounding. Many plans offer an “auto-escalation” feature that automatically increases your contribution percentage by a set amount each year, which is an excellent way to effortlessly maximize 401(k) 2026 and beyond.
4. Utilize Catch-Up Contributions (If Age 50+)
If you’re 50 or older, take full advantage of catch-up contributions. This additional amount allowed by the IRS is specifically designed to help older workers boost their retirement savings as they near retirement. For 2026, this could add an extra $7,500 – $8,500 to your annual contribution, making a substantial impact on your retirement nest egg.
5. Understand Your Plan’s Investment Options
Maximizing your 401(k) isn’t just about how much you contribute; it’s also about how your money is invested. Review your plan’s investment options regularly. Ensure your asset allocation aligns with your risk tolerance and time horizon. Diversify your investments across different asset classes (stocks, bonds, real estate, etc.) to mitigate risk and optimize returns. If you’re unsure, target-date funds can be a good hands-off option, as they automatically adjust their asset allocation as you approach retirement.
6. Consider a Roth 401(k) Option
If your employer offers a Roth 401(k), consider whether it’s a good fit for your financial situation. With a Roth 401(k), contributions are made with after-tax dollars, meaning qualified withdrawals in retirement are tax-free. This can be particularly advantageous if you expect to be in a higher tax bracket in retirement than you are now. It also offers diversification in terms of tax treatment, which can be beneficial for managing your tax liability in retirement.
7. Plan for Bonuses and Tax Refunds
When you receive a bonus or a tax refund, consider directing a portion of it directly into your 401(k). This can be an effective way to make a lump-sum contribution or increase your regular contributions without impacting your regular budget. This extra injection of funds can help you reach the annual contribution limit faster and enhance your overall savings.
Common Pitfalls to Avoid When Trying to Maximize 401(k) 2026
While the goal is to maximize your 401(k), there are common mistakes that can hinder your progress. Being aware of these can help you steer clear of them:
1. Not Contributing Enough to Get the Employer Match
As mentioned, this is the biggest mistake. It’s literally leaving money on the table. Always contribute at least enough to get the full match.
2. Cashing Out Your 401(k) When Changing Jobs
When you leave a job, you might be tempted to cash out your 401(k). This is almost always a bad idea. Cashing out typically incurs income taxes plus a 10% early withdrawal penalty if you’re under 59½. Instead, roll over your 401(k) into your new employer’s plan (if allowed), an IRA, or keep it with your old employer if the fees are low and investment options are good. This preserves your tax-advantaged savings and avoids penalties.
3. Being Too Conservative or Too Aggressive with Investments
Your investment strategy should align with your age and risk tolerance. Being too conservative (e.g., investing mostly in cash or stable value funds) can lead to insufficient growth, especially when you’re young. Being too aggressive (e.g., all in on volatile stocks) close to retirement can expose you to significant market downturns with little time to recover. Rebalance your portfolio periodically to maintain your desired asset allocation.
4. Ignoring Fees
401(k) plans come with various fees, including administrative fees, investment management fees (expense ratios), and transaction fees. While some fees are unavoidable, high fees can significantly erode your returns over time. Review your plan’s fee disclosure statement and opt for lower-cost investment options when available. Even a difference of 0.5% in fees can translate to tens of thousands of dollars over a few decades.
5. Not Reviewing Your Beneficiaries
Life changes, and so should your beneficiary designations. Make sure your 401(k) beneficiaries are up to date. If you get married, divorced, or have children, update your beneficiaries to ensure your assets go to your intended heirs. Beneficiary designations supersede wills, so it’s crucial to keep them current.
Advanced Strategies and Considerations for 2026
Once you’ve mastered the basics and implemented the core strategies, consider these advanced tactics to further maximize 401(k) 2026 and your overall retirement planning:
1. The Mega Backdoor Roth (If Your Plan Allows)
This advanced strategy allows high-income earners to contribute significantly more to a Roth account than the standard Roth IRA limits. If your 401(k) plan allows after-tax non-Roth contributions and in-service distributions (or conversions), you can contribute after-tax money to your 401(k) up to the overall total contribution limit (employee + employer, projected to be $69,000 – $72,000 for 2026) and then convert those after-tax funds to a Roth IRA. This effectively allows you to get more money into a Roth account, where it can grow and be withdrawn tax-free in retirement. Consult a financial advisor to see if this strategy is suitable for you and if your plan supports it.
2. Understanding Your Vesting Schedule
Employer contributions (matching and profit-sharing) often come with a vesting schedule, meaning you must work for the company for a certain period before you fully own those contributions. If you leave before you are fully vested, you might forfeit some or all of the employer’s contributions. Understand your plan’s vesting schedule, especially if you anticipate changing jobs. This knowledge can influence your decision on when to leave a company to ensure you don’t miss out on vested employer contributions.
3. Coordinating with Other Retirement Accounts
Your 401(k) is likely just one piece of your retirement puzzle. Coordinate your 401(k) strategy with other retirement accounts like IRAs (Traditional or Roth), HSAs (Health Savings Accounts), and taxable brokerage accounts. For instance, an HSA is often referred to as a “triple tax-advantaged” account (tax-deductible contributions, tax-free growth, tax-free withdrawals for qualified medical expenses), making it an excellent complementary retirement savings vehicle if you have a high-deductible health plan. A holistic approach ensures you’re optimizing all available avenues for retirement savings.
4. Regular Financial Review and Adjustments
Your financial situation, goals, and market conditions are not static. Schedule annual reviews of your retirement plan. This includes checking your 401(k) performance, re-evaluating your contribution rate, adjusting your investment allocation, and ensuring your overall retirement strategy remains on track. Life events such as marriage, children, career changes, or unexpected expenses should also trigger a review of your retirement plan.
The Importance of Starting Early and Staying Consistent
While focusing on 2026 is important, the overarching principle of retirement savings is to start as early as possible and remain consistent. The magic of compounding interest works best over long periods. Even small contributions made early in your career can grow into substantial sums by retirement. Conversely, delaying contributions means you’ll have to save significantly more later to catch up.
Consistency is key. Life will throw financial curveballs, but maintaining your contribution schedule, even during challenging times, will pay dividends in the long run. If you must reduce contributions temporarily, make it a priority to increase them again as soon as your financial situation improves.
Conclusion: Your Path to a Secure Retirement Through Maximizing 401(k) 2026
Maximizing your 401(k) in 2026 is a crucial step towards building a secure and comfortable retirement. By staying informed about the latest contribution limits, strategically planning your contributions, taking advantage of employer matches and catch-up contributions, and making smart investment choices, you can significantly boost your retirement savings. Avoid common pitfalls, explore advanced strategies, and consistently review your plan to ensure you’re always on the right track.
Don’t underestimate the power of proactive planning and consistent effort. Your future self will thank you for taking the time today to understand and implement these strategies to maximize 401(k) 2026. If you’re unsure about any aspect of your retirement planning, consider consulting with a qualified financial advisor who can provide personalized guidance tailored to your unique circumstances and goals.